Debt Payoff Planner & Tracker

Screenshots
Details
- Rating
- 1.22K reviews
- Version
- 2.54
- Developer
- Easily get a plan and stick to it - OxbowSoft LLC
Analysis by Norviv
When I’m trying to get a handle on several balances at once, the hardest part is often turning a vague intention to pay them down into a plan I can follow. Debt Payoff Planner & Tracker is built around that practical problem: you enter your debts, compare payoff approaches, and use a plan to keep track of progress. I see it as a focused finance app rather than an all-purpose budgeting tool. It is most useful when you already know what you owe and want a clearer way to decide what to tackle next.
Where the app fits today
The app comes from Easily get a plan and stick to it - OxbowSoft LLC, and it has been available since January 8, 2015. Its current version is 2.54, which gives existing users a concrete point of reference when checking compatibility or considering an update. It is free to download, with in-app purchases ranging from $6.99 to $41.99 per item. The age rating is Everyone, and it requires Android 6.0 or later.
Its reach suggests that this is an established option in the debt-planning space: it has more than 500,000 installs, a 4.5 average from around 4,600 ratings, and about 1,200 written reviews. Those figures can help set expectations about its audience, but they don’t tell me whether its approach will suit every household. Debt planning depends on the accuracy of the numbers you enter and on whether you can keep following the plan when expenses change.
The app’s central appeal is its narrow focus. Rather than asking me to manage every part of my financial life in one place, it concentrates on debts and payoff order. That can be a relief if budgeting dashboards, account categories, and spending charts distract from the immediate question: how should I direct the money available for repayment?
How I would build a plan that survives real life
I would start by gathering each current balance, interest rate, and required payment before entering anything. A small error in a rate or minimum can make a payoff estimate misleading, so I’d use recent statements rather than memory. I’d also check whether the payment amount I can afford is realistic after rent, bills, groceries, and a modest cushion for irregular costs. A plan that assumes every spare dollar will be available is likely to break the first time a car repair or medical bill appears.
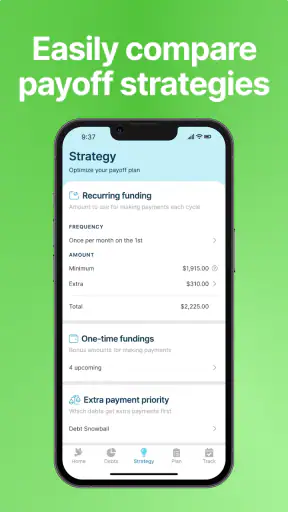
Once the figures are in place, the app’s payoff strategies help make the trade-off more visible. The familiar Avalanche approach prioritizes the highest interest rate, while Snowball puts the smallest balance first. I’d compare both plans before committing. Avalanche may be the more cost-conscious choice when interest rates differ substantially and I can stay motivated without quick wins. Snowball may feel more manageable when clearing an account gives me the momentum to keep going. Neither method can choose my priorities for me; the useful part is seeing how a chosen order shapes the route.
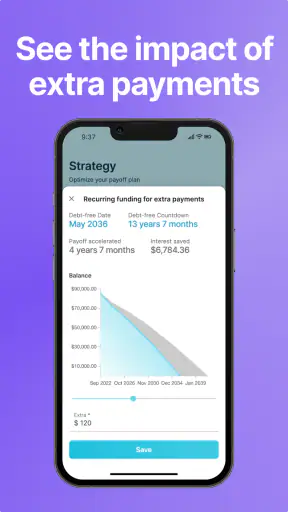
One practical habit is to revisit the plan after a meaningful change rather than treating the first estimate as permanent. If a balance falls faster than expected, a rate changes, or my monthly repayment budget shrinks, I’d update the inputs and check whether the order still makes sense. This is also a good point to separate money already committed to minimum payments from any extra amount I intend to direct to the target debt. That distinction makes it easier to avoid confusing the plan’s ideal pace with what my budget can actually support.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
For example, imagine I’m paid near the end of the month and have several balances with different rates. I could use a few minutes after reviewing my bills to confirm the current balances, decide what extra repayment is genuinely available, and check which debt the selected strategy puts first. After making a payment, I’d update the relevant balance instead of assuming the app knows it happened. That small routine turns the planner into a record I can act on, rather than a forecast I glance at once and forget.
What its tracking can—and cannot—do
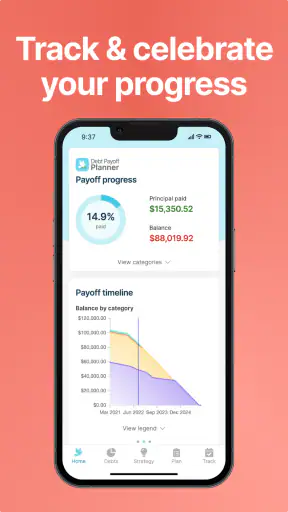
Progress indicators can make an otherwise abstract goal easier to see. A balance shrinking is not always noticeable from one statement to the next, so a visual marker can provide a useful prompt to keep the routine going. I would treat that as motivation, not as proof that my overall finances are healthy. The tracker is concerned with the debt plan; it does not replace a full view of spending, savings, and upcoming obligations.
There is also a useful trade-off in the app’s manual approach. The published app description and the experience represented here focus on entering and following a plan, rather than automatically connecting to bank accounts. That means I have to maintain the figures myself, which adds a little ongoing work and leaves room for stale balances if I stop updating them. In return, I can decide exactly what information I enter instead of relying on an automatic feed. Someone who wants a single app to import transactions and categorize everyday spending may prefer a broader budgeting service.
I would not assume that a projected payoff date is a promise. Estimates depend on the balances, rates, and payments entered, and real repayment schedules can be affected by changing circumstances. If an account has fees, a promotional rate, or a payment arrangement with special terms, I’d read the lender’s terms and use the planner as a way to organize decisions—not as a substitute for checking how that account works.
The free download makes it possible to try the basic idea before paying, but the in-app purchase range means I’d check which specific tools are included in the option I’m considering. I wouldn’t pay simply because I felt pressured to unlock something while already worried about debt. First I’d test whether keeping the inputs current and following a payoff order actually helps me; only then would I decide whether a paid item is worth fitting into my budget.
Who is likely to get the most from it
I think the planner is a good fit for someone with more than one debt who wants a clear repayment order and is comfortable entering figures manually. It may also help a person who has tried to make a plan in notes or a spreadsheet but finds it hard to keep the goal visible. The combination of strategy choices and progress tracking gives the repayment process a defined next step without requiring me to turn the task into a complicated financial project.
It is less suited to someone who needs automatic transaction imports, a complete household budget, or detailed financial advice. It also may not be the right first step for a person whose income does not cover required payments or essential bills. In that situation, a payoff schedule alone cannot resolve the shortfall; contacting lenders or a qualified financial counselor may be more useful than trying to optimize the order of debts in an app.
Compared with a spreadsheet, the app offers a more guided debt-specific workflow and a visual sense of progress, while a spreadsheet gives me more freedom to build custom calculations and include other parts of my finances. Compared with a broad budgeting app, this planner keeps attention on repayment rather than spending categories. The better choice depends on the task: I’d choose this one when I need a debt payoff structure, and a broader tool when my main problem is understanding where my money goes each month.
What Does It Do?
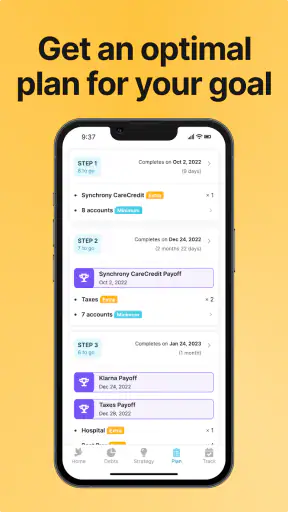
The Debt Payoff Planner & Tracker is essentially your personal financial sidekick, designed to help you manage and pay off your debts in a structured way. You start by inputting all the debts you have, whether it’s credit card bills, student loans, or even that pesky car loan. The app then works its magic and creates a customized payoff plan just for you.
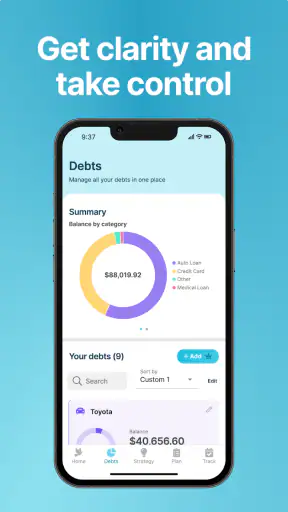
What I really liked is how it breaks down the numbers. You get to see how much you owe, the interest rates, and the estimated time it’ll take to pay everything off. It’s like having a financial advisor in your pocket, without the hefty fees!
Key Features
One of the standout features for me was the ability to choose different payoff strategies. The app lets you select between methods like the Avalanche or Snowball. If you’re not familiar, Avalanche tackles the highest interest rates first, while Snowball focuses on the smallest debts. Personally, I went with the Snowball method because I love the feeling of knocking out smaller debts quickly.
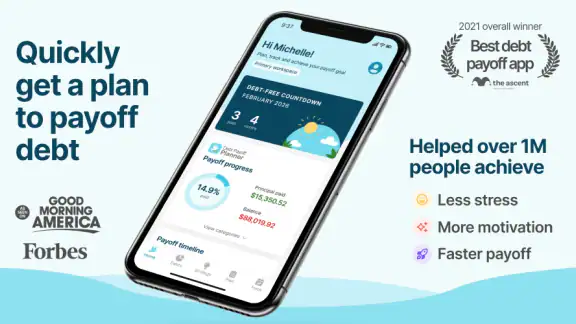
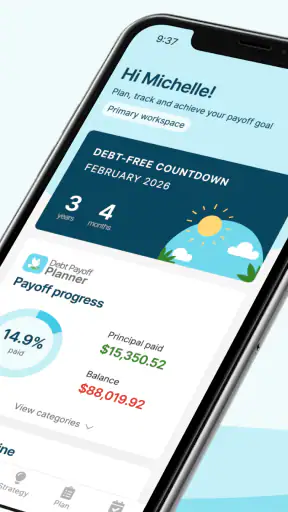
Another cool aspect is the progress tracking. There’s nothing more satisfying than seeing that little progress bar move as you make payments. It’s a visual reminder that you’re on the right path.
User Experience
Let’s talk about the user interface. The app is super intuitive and easy to navigate. Even if you’re not a tech whiz, you’ll find it straightforward. Inputting data is a breeze, and the dashboard gives you a clear overview of your financial health.
Also, the app offers notifications and reminders, which I found extremely helpful. It’s like having a gentle nudge that keeps you accountable. No more forgetting when payments are due!
Potential Drawbacks
While the app is pretty solid, there are a few things to keep in mind. For starters, the free version is somewhat limited. To unlock all the features, you might need to consider a premium subscription. It’s something to weigh against your budget, but if you’re serious about getting debt-free, it could be a worthwhile investment.
Another thing is, the app doesn’t link directly to your bank accounts. Some users might find this a downside, but on the flip side, it means you have full control over your data without any security worries.
Final Thoughts
At the end of the day, Debt Payoff Planner & Tracker is a fantastic tool if you’re looking to take charge of your finances. It’s user-friendly, offers a variety of payoff strategies, and keeps you motivated with progress tracking. Sure, there are some limitations with the free version, but the peace of mind it offers is priceless.
If you’re ready to tackle your debts head-on, I’d definitely recommend giving this app a try. It’s a step towards financial freedom, and who doesn’t want that?
So, what are you waiting for? Dive in and start planning your debt-free journey today!
Frequently Asked Questions
01What is the Debt Payoff Planner & Tracker app used for?
The Debt Payoff Planner & Tracker app is designed to help users manage and eliminate their debts systematically. It provides tools and strategies, such as the snowball and avalanche methods, to create personalized plans. Users can track progress, set goals, and visualize timelines to achieve debt freedom effectively.
02Is the Debt Payoff Planner & Tracker app secure for managing personal financial information?
Yes, the app is built with security in mind to protect users' financial data. It uses encryption and secure storage practices to ensure sensitive information, such as account balances and payment details, remains confidential. However, users should also follow best practices like using strong passwords and keeping their devices secure.
03Does the app support multiple types of debt?
Absolutely, the Debt Payoff Planner & Tracker app supports a wide range of debt types, including credit cards, student loans, mortgages, and personal loans. Users can input different debts and the app will provide a consolidated plan to tackle all debts simultaneously, offering a comprehensive overview of finances.
04Can I customize my debt repayment plan in the app?
Yes, the app allows full customization of your debt repayment plan. Users can choose between different strategies like the snowball or avalanche methods, adjust monthly payments, and set target payoff dates. This flexibility helps users tailor their plans to fit their financial situations and goals.
05Is there a cost associated with using the Debt Payoff Planner & Tracker app?
The app offers a free version with basic features, allowing users to track and plan their debt repayment. For advanced features, such as detailed analytics, priority support, or additional customization options, there may be a subscription fee. It's advisable to review the app store listing for the latest pricing details.


